France’s 4.93% borrowing cost is locked in
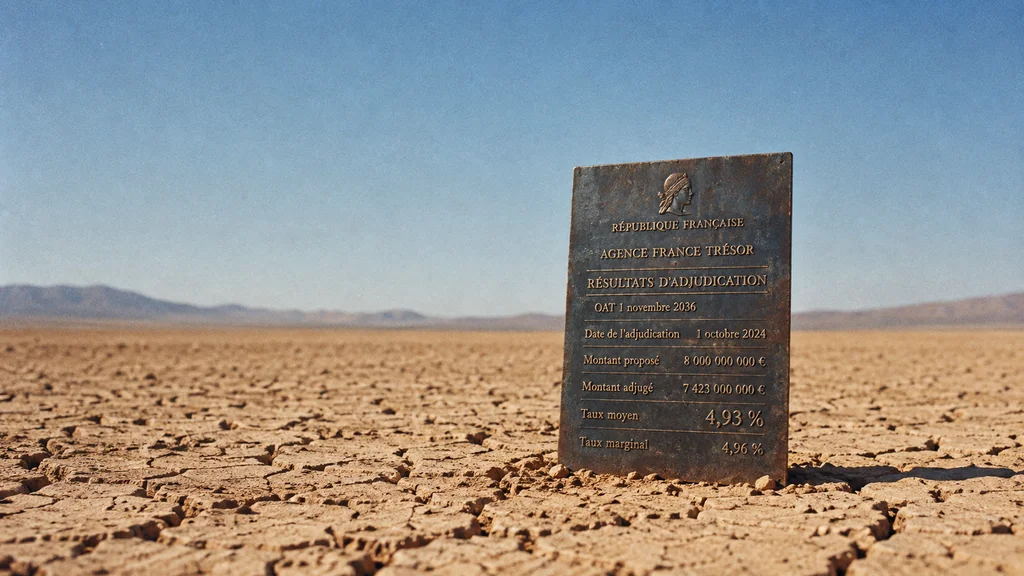
France’s October borrowing cost stays fixed as market yields retreat.
Image composition · tobriefOn 1 October, France sold €6.271 billion of a bond maturing in November 2036 at an average yield of 4.93%, up from 4.23% when it sold the same bond on 3 September (auction result/Boursorama). Market yields peaked the next day, when France's ten-year yield hit 4.993% (Reuters/MarketScreener), and have eased since. That easing cannot change the price France accepted at the October sale.
A yield is the yearly return investors demand for holding a bond at its current price. The spread is the French yield minus the German one. It measures the extra return investors want for lending to Paris rather than Berlin. On Friday 2 October that gap touched 158.67 basis points, where a basis point is 0.01 percentage point (Reuters/MarketScreener).
The gap reflects doubts that Prime Minister Sébastien Lecornu can pass a deficit-cutting 2027 budget through a divided parliament, a pressure we tracked as it built last week (To Brief). On Monday morning those doubts were still driving trades. Investors sold French bonds and bought German ones, so France's yield rose 1.8 basis points while Germany's fell 2.3 (Reuters/LSE).
Tuesday's relief was partly global
By late Tuesday morning, Reuters quoted France at 4.7526% and Germany at 3.4613%, a gap of about 129 basis points (Reuters/Boursier). Part of that fall had nothing to do with Paris.
Oil prices dropped and inflation worries cooled. Lower expected inflation means investors need less compensation for holding bonds, so yields fell in many countries. In one Reuters snapshot, the French yield fell 15.3 basis points, the German 4.6 and the US ten-year 4.4 (Reuters/LSE). France fell further than the others, which means its own premium shrank as well.
Italy moved with France. At 10:31 on Tuesday, Teleborsa quoted Italian yields at 4.51% and French yields at 4.75%, against 3.44% for Germany (Teleborsa/Repubblica). Spain paid less of a premium, even though Prime Minister Pedro Sánchez has called a snap election. On the same day, its ten-year yield stood at 4.082%, about 63 basis points over Germany (EFE). That quote shows far less pressure on Spain than on France, although it cannot show how much Spain's premium moved.
Why the October sale stays expensive
Higher market yields do not change the cost of debt France has already issued. Those bonds pay a fixed coupon, the yearly interest promised when they were sold. When yields rise, their market price falls. The loss lands on investors who sell them, not on the government.
New borrowing works differently. The 2036 bond pays a coupon fixed when it was first issued. When investors demand a higher yield, they pay less for each bond. France still owes the full face value at maturity and every coupon until then. Selling at the October yield instead of the September one therefore raised less cash for the same promise to repay.
That higher cost is now locked in on this slice of debt until 2036. Its effect on France's total interest bill depends on the yields Paris faces at the many auctions still to come.
The ECB (the European Central Bank, which sets interest rates for the eurozone) has a tool, launched in July 2022, for buying a country's bonds to counter "unwarranted and disorderly" market moves. The ECB decides whether to use it, and it can hold back if the pressure comes from a country's own budget problems (ECB).
France's latest sale of its 2036 bond funded the state at a higher yield than the September sale of the same bond, and Tuesday's rally cannot revise that. One sale does not settle how large France's debt bill will become. That depends on yields at future auctions, which will follow both the fate of Lecornu's budget and global bond markets that Paris does not control.
Details about this article
- Model:
- claude-opus-5-5
- Generated:
- 10/7/2026, 1:40:00 AM
- Pipeline run:
- eu_pipeline_20261007_005007
- Watermark:
- SynthID (Google's invisible watermark)
- Human review:
- None before publication